The Accidental Landlord: How Inheriting Chicago Real Estate Can Become a Legal Nightmare
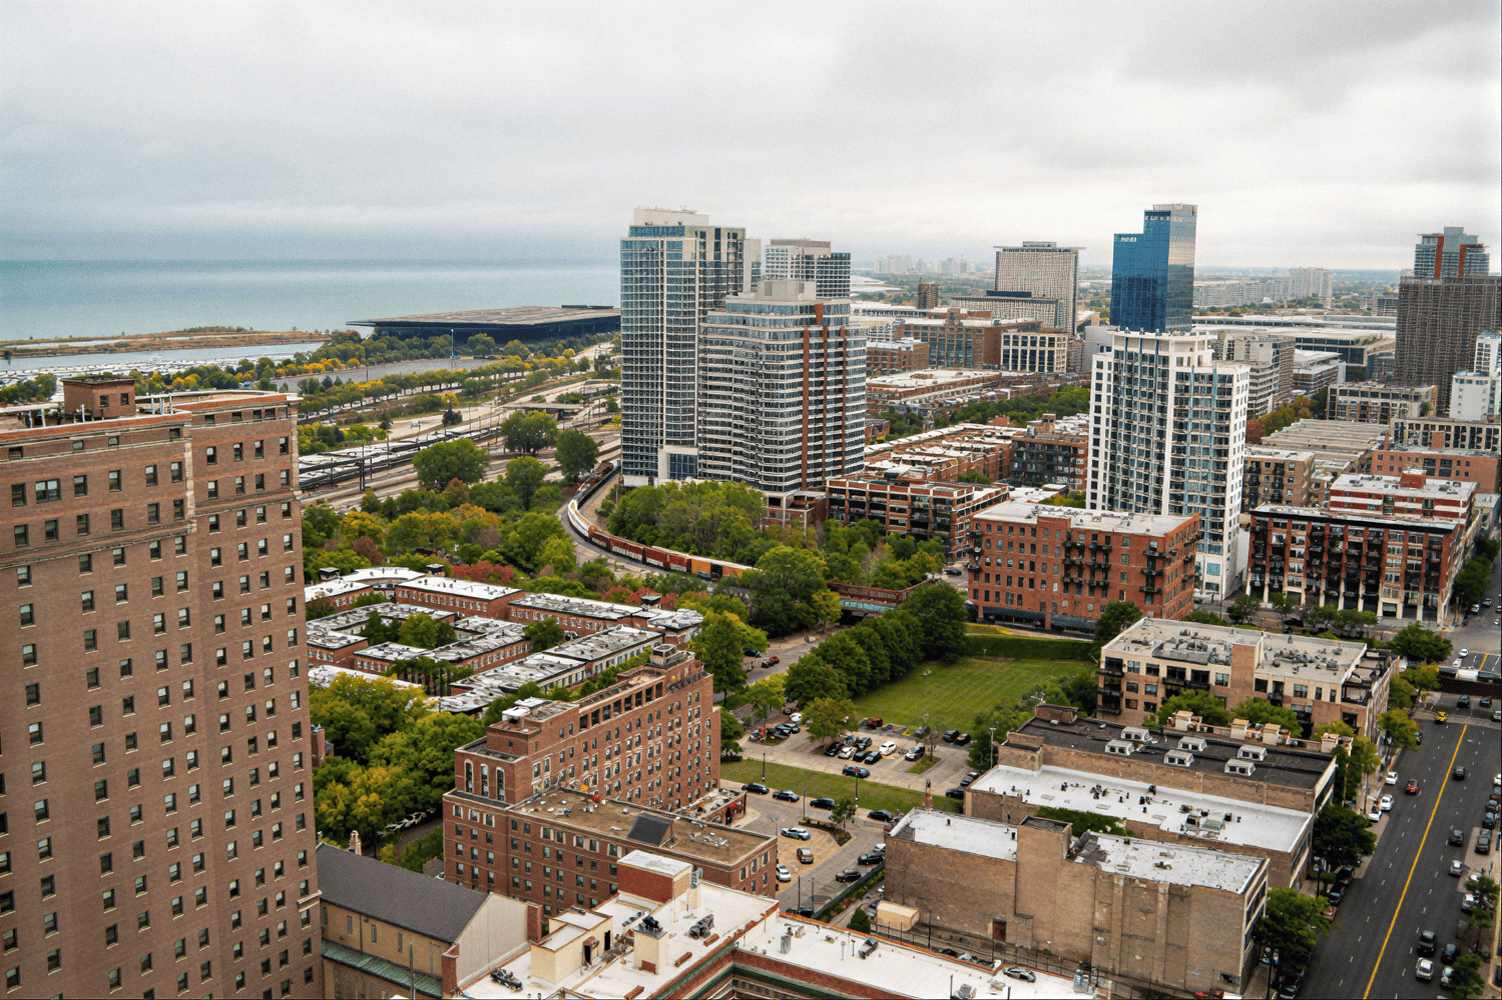
Across Chicago neighborhoods, historic brick two-flats, classic three-flats, and multi-family brownstones are more than just architecture; they are generational cornerstones. Parents and grandparents often spent decades paying off mortgages, caring for tenants, and building equity to pass down as a lasting foundation for their children.
Yet, when that inheritance happens without proactive legal structuring, the intended gift can quickly unravel into an overwhelming legal burden.
As National Estate Planning Awareness Month winds down this October, it provides a crucial moment to address one of the most overlooked estate planning dilemmas: the “accidental landlord.” When an heir inherits income-generating real estate without clear authority, management protocols, or court-free legal vehicles, a cherished family property can quickly devolve into family disputes, severe municipal code penalties, and frozen finances.
Here is how inherited real estate becomes a legal nightmare under Illinois law, along with the practical safeguards needed to protect your family’s investment.
1. The Probate Freeze: Income, Maintenance, and Mortgages Trapped in Court
When an owner passes away holding real estate solely in their individual name, or with only a basic will, that property cannot simply transfer to the heirs overnight. It must pass through the Cook County probate court.
Probate in Illinois regularly stretches from nine to eighteen months or longer. During this limbo:
- Rental income may be frozen in estate-controlled accounts rather than disbursed to cover property expenses.
- Heirs frequently lack immediate legal standing to sign leases, address non-paying tenants, or access bank accounts to pay utility bills and insurance premiums.
- If a boiler fails in mid-winter, heirs often have to pay thousands of dollars out of pocket while waiting for the court to formally issue letters of office to an executor.
The Fix: Transfer real estate into a fully funded revocable living trust. A living trust allows your appointed successor trustee to step in immediately upon incapacity or death, managing tenants, paying maintenance bills, and keeping the building operating smoothly without having to set foot in probate court.
2. The Sibling Stalemate: Co-Ownership Without an Operating Strategy
Leaving a multi-unit property equally to multiple adult children sounds fair on paper. In practice, titling real estate to siblings as tenants in common without a governing entity often triggers intense family conflict.
Real-world friction quickly emerges:
- One child wants to keep renting the building for passive income, while another lives out of state and wants to cash out immediately.
- One heir volunteers their weekends for hands-on maintenance, while another refuses to contribute toward roof repairs or property tax installments.
- When a deadlock occurs, Illinois partition actions allow a single co-owner to petition a court to force the sale of the building at public auction, eroding equity and breaking family bonds.
The Fix: Structure ownership within an LLC or a trust agreement that features clear governance rules. Your plan should clearly define decision-making authority, establish buy-out mechanisms for heirs who wish to exit, and set aside dedicated reserves for property upkeep.
3. The Regulatory Blindside: Municipal Landlord Ordinances and Personal Liability
Managing rental property in Chicago involves strict statutory compliance. Under local tenant protection rules, such as the Chicago Residential Landlord and Tenant Ordinance (RLTO), property owners face severe statutory penalties for common procedural missteps.
Inexperienced heirs rarely know the operational complexities:
- Mismanaging tenant security deposits or failing to hold them in separate, interest-bearing accounts can trigger mandatory statutory penalties, attorney fee awards, and tenant lawsuits.
- Unaddressed building code notices, annual heating requirements, and fire safety compliance remain the legal responsibility of the title holder.
- If insurance policies are not promptly updated from the deceased owner’s name to the estate, trust, or heirs, an unforeseen liability claim (such as a slip-and-fall) can expose heirs to personal financial exposure.
The Fix: Incorporate risk management and tenant transition protocols into your estate plan. Pair your trust with umbrella liability coverage and provide an organized directory of existing leases, security deposit ledgers, service contracts, and licensed property managers.
4. The Tax Assessment Shock: Misplaced Exemptions and Frozen Appeals
Property taxes are among the heaviest ongoing expenses for Chicago’s residential and commercial property owners. When a family home or multi-unit property passes down, tax assessments frequently spike without warning.
When an elderly parent passes away, their senior citizen exemptions, senior freezes, and homeowner exemptions expire. If heirs do not actively monitor Cook County assessment cycles, reassessment notices, and appeal windows, the annual tax bill can double unexpectedly. Missing property tax appeal deadlines during an ongoing probate administration leaves the property saddled with an inflated valuation for years.
The Fix: Combine your estate plan review with an ongoing property tax strategy. Make sure your legal counsel understands both real estate transfers and local property tax assessment calendars to preserve maximum tax relief across generations.
5. Liquidity Shortages: An Asset-Rich, Cash-Poor Inheritance
A multi-unit building is a high-value, illiquid asset. Even after the mortgage is paid off, maintaining a vintage Chicago building requires steady liquidity for water bills, scavenger services, property taxes, structural maintenance, and insurance premiums.
When parents pass down real estate without leaving dedicated liquid funds, heirs are forced to fund property shortfalls from their personal checking accounts. If heirs cannot afford the carrying costs, they are often forced into an urgent, below-market distress sale just to satisfy delinquent tax liens or utility bills.
The Fix: Integrate liquidity planning into your trust. Balancing real estate gifts with life insurance proceeds or dedicated savings reserves inside the trust ensures your heirs have the working capital needed to preserve the building while transitioning management.
Keep Your Family Legacy Protected and Out of Court
Inheriting a family property should represent a meaningful step forward, not a stressful descent into court litigation and tenant disputes. With proper structuring, your family home or neighborhood building can remain an enduring source of security, pride, and generational stability.
At Marshiano Law Group, Tony Marshiano combines comprehensive estate planning counsel with decades of hands-on real estate and property tax experience. We help Chicago families build protective, court-free plans that keep their homes, savings, and investments secure for generations to come.
Protect your real estate investment before complications arise.
Call (312) 965-1111 or visit www.marshianolawgroup.com today to schedule your comprehensive estate plan review.